Year-End Insurance Review: Home, Auto, and More
The end of the year is an ideal time to take a fresh look at your insurance. A good review is not only about the premium—it is about whether your home, vehicles, belongings, and liability...
Read more
Keeping Homes Safe While Traveling
Travel plans should be an opportunity to relax, spend time with loved ones, and enjoy a change of scenery—not a reason to worry about what is happening at home. Whether you are leaving Southwest...
Read more
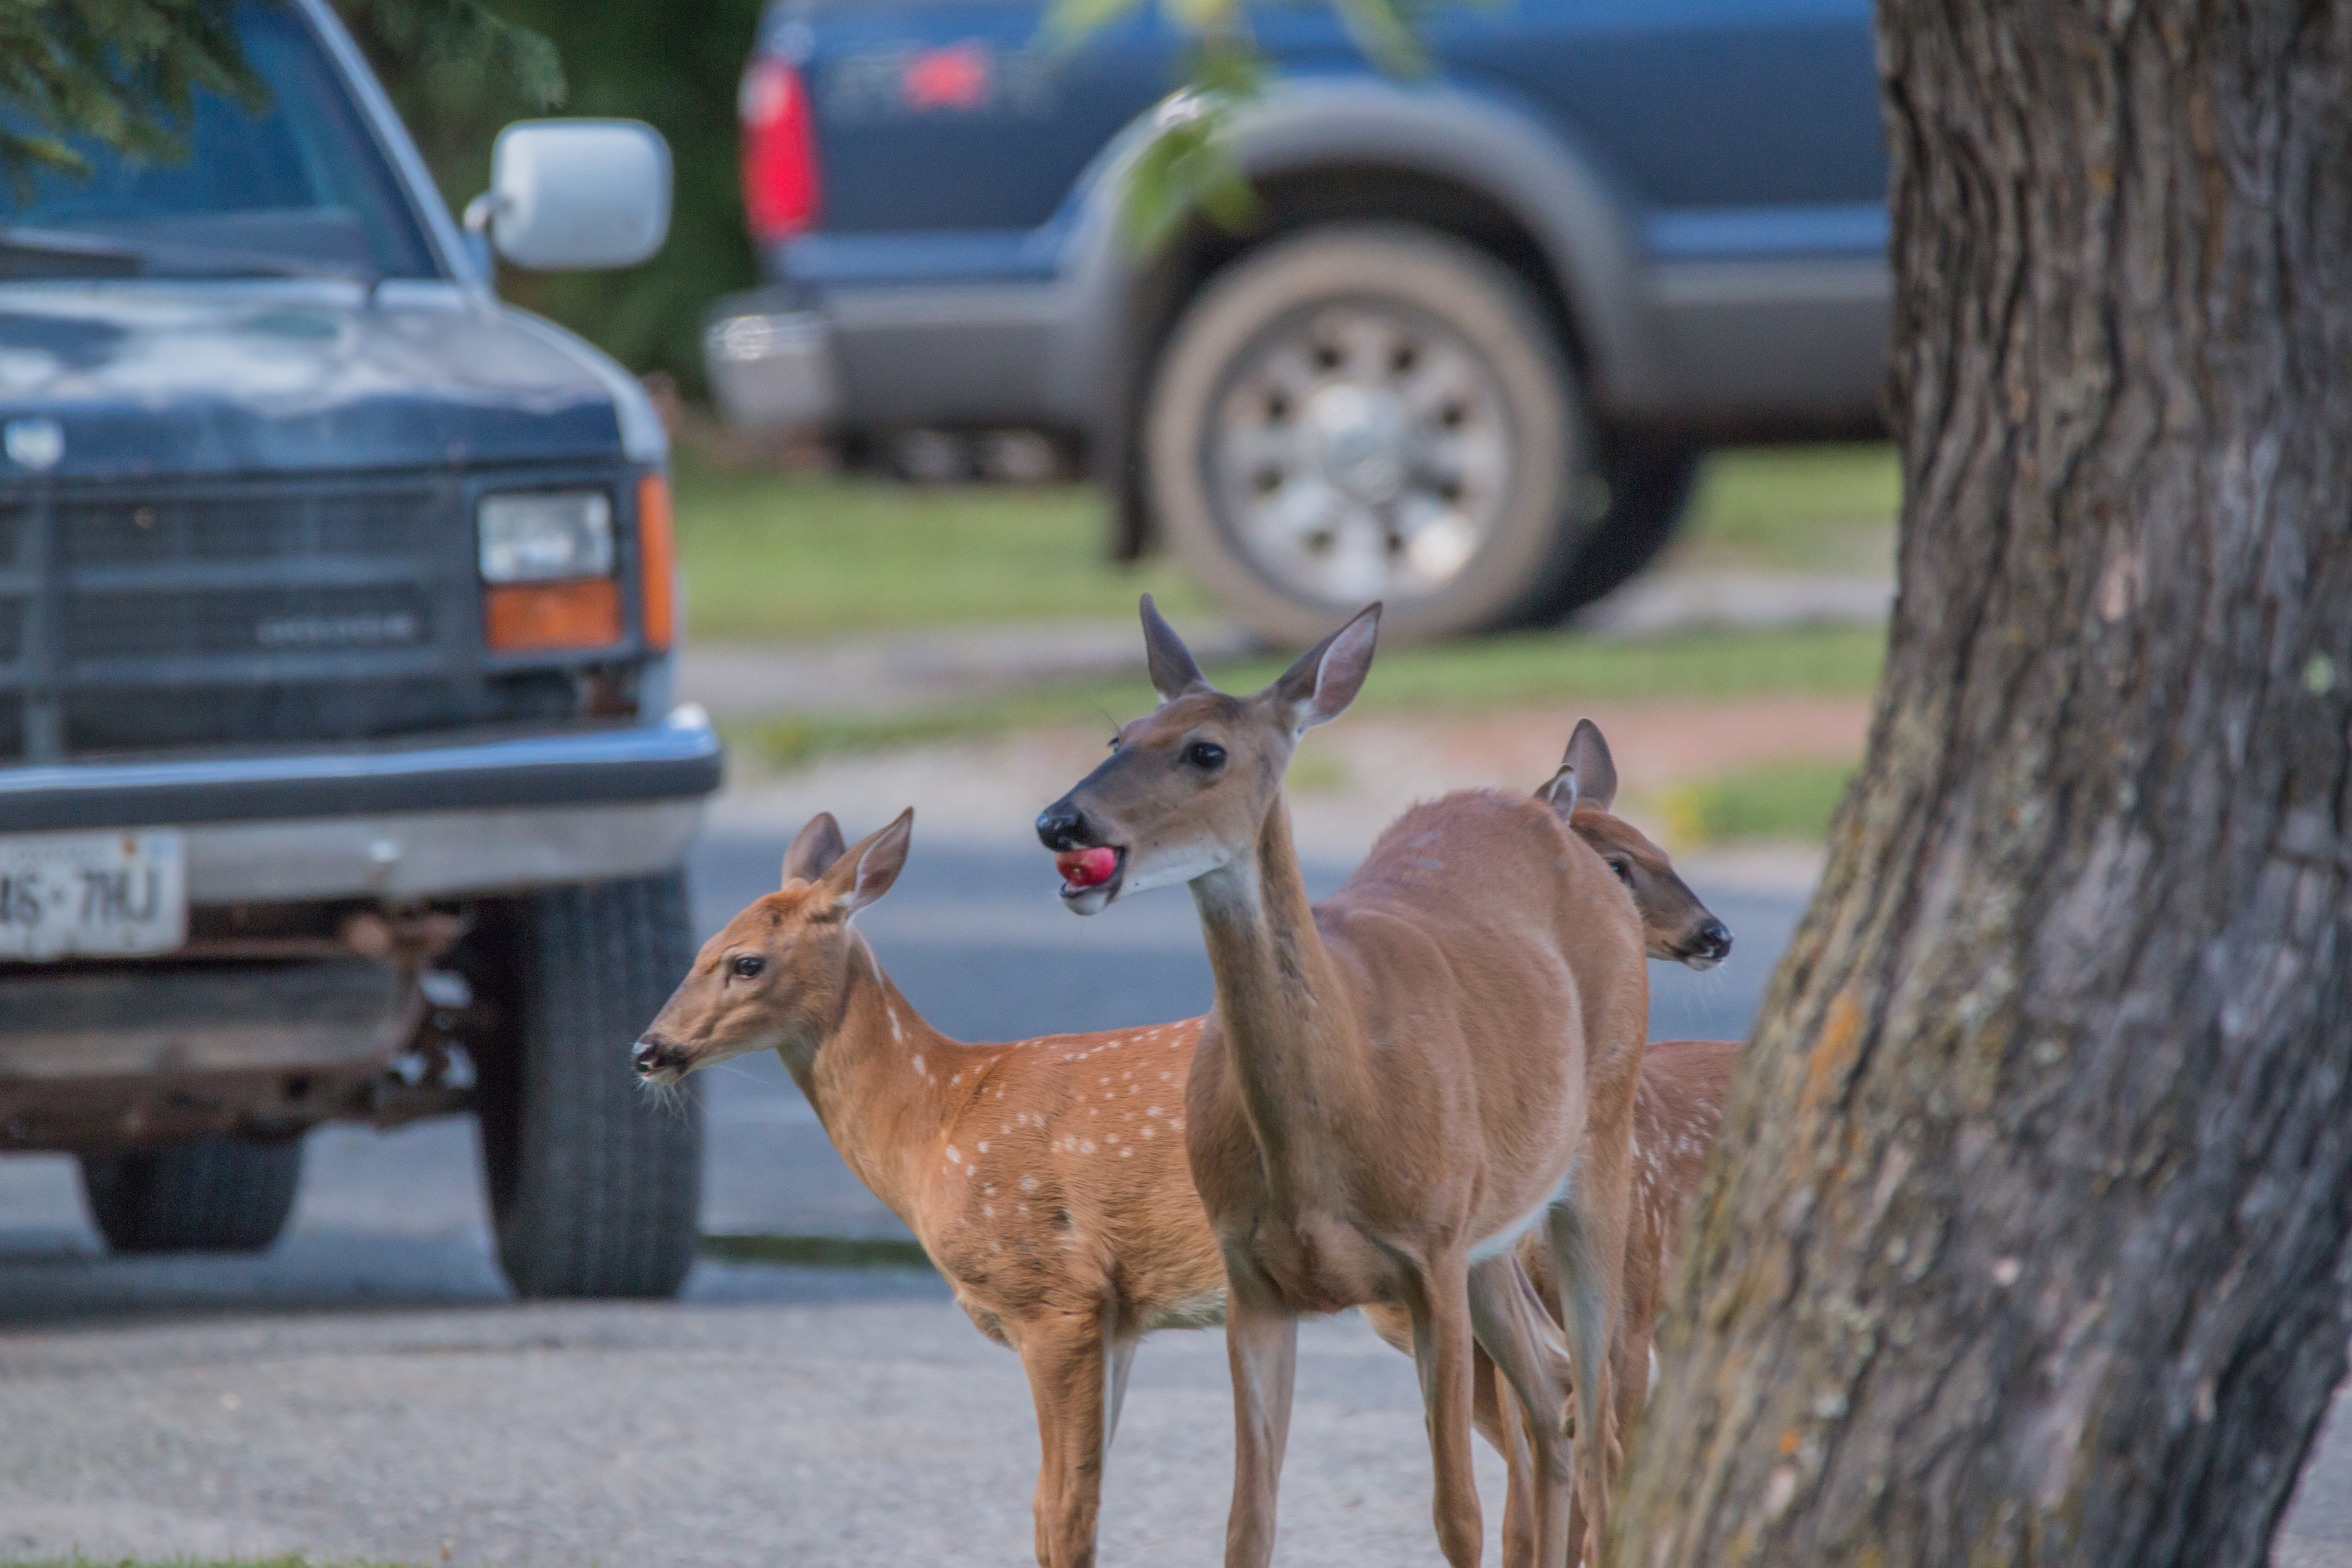
Deer Collision Reminder - Safety Tips - Personal
Shorter days and increased deer activity in the fall can create a heightened risk for drivers. Understanding why deer are more active and knowing how to stay alert can make a significant difference...
Read more
Long-Term Care Planning Month - October
Long-term care planning is an essential part of preparing for the years ahead, even though it’s often overlooked in traditional retirement conversations. While many people envision an independent...
Read more
Deer Collision Reminder - Safety Tips - Commercial
Shorter days and higher wildlife activity make fall a challenging season for anyone operating a commercial vehicle. As deer become more active during these months, businesses across Southwest...
Read more
100 Days Left of the Year - What Has Changed in Your Life
As the year begins to wind down, many people start reflecting on the goals they’ve completed, the milestones they’ve hit, and the changes that have shaped their routines at home and work. It’s also...
Read more
Fall Prep Tips for Residential Properties
As cooler weather approaches, fall is the ideal time for homeowners to prepare their property for the months ahead. Taking care of routine upkeep now can help prevent small concerns from turning...
Read more
Trucker Simulation Training
Simulation training has become a valuable tool for commercial fleets looking to enhance driver safety, reduce liability exposure, and improve operational efficiency. By integrating realistic...
Read more
Back-To-School Safety Reminders
As families across Southwest Florida gear up for another school year, this season often brings early alarms, packed lunches, and new routines. It also offers an ideal opportunity to revisit key...
Read more
Fall Prevention Awareness Month - Sept. - Tips for Businesses
September’s Fall Prevention Awareness Month is a timely reminder for businesses to re-evaluate how they handle everyday safety risks. Slip, trip, and fall incidents continue to be among the most...
Read more
Cyber Insurance for Businesses: What You Need to Know
Cyber threats have become a major concern for organizations of every size, and many business owners are now recognizing just how disruptive a digital incident can be. From ransomware to phishing...
Read more
National Traffic Awareness Month - August - A Back-to-School Reminder
This time of year brings major changes to local roadways as students return to class across Southwest Florida. Families, school staff, and drivers all experience shifts in traffic flow, especially...
Read more
Insurance & College Students - Key Considerations
Sending a student off to college marks an exciting transition filled with new routines, independence, and responsibilities. While families often dedicate a lot of time to academics, housing, and...
Read more
Commercial Umbrella Liability
Running a business comes with daily responsibilities, long‑term planning, and the constant possibility of unexpected risks. Even with standard business insurance in place, there can still be...
Read more
Does Auto Insurance Follow the Car or the Driver?
Many drivers are unsure whether auto insurance applies to the vehicle, the driver, or both. This question often comes up when lending your car to a friend or borrowing someone else’s vehicle. While...
Read more
Employment Practices Liability Insurance Deep Dive
Employment disputes can surface unexpectedly, and even a routine workplace decision can evolve into something far more complicated. Employment Practices Liability Insurance (EPLI) helps shield...
Read more
When Business Growth Outpaces Insurance Coverage
Business growth is exciting, but it can also create quiet gaps in your insurance protection. As operations expand, many small changes—new equipment, more inventory, additional staff, or bigger...
Read more
Boat Liability Risks Most Owners Don’t Think About
Many Florida boat owners look forward to sunny days on the water, but it’s easy to overlook whether your coverage truly reflects the risks that come with boating. While cruising through places like...
Read more
Pool, Trampoline & Backyard Liability - Are You Covered This Summer?
Summer in Southwest Florida brings plenty of outdoor fun, from family cookouts to lazy afternoons by the pool. Many homeowners also look forward to refreshing their backyards with pools,...
Read more
Hurricane Season Prep Tips for Homeowners
Hurricane season brings significant risks to Florida communities, from strong winds and flooding to extended power outages. Preparing early helps protect your property, reduce stress, and ensure...
Read more
Distracted Driving Awareness Month: How to Stay Safe Behind the Wheel
April marks Distracted Driving Awareness Month, offering a meaningful reminder to reflect on our habits whenever we get behind the wheel. Many crashes occur not because of poor weather or hazardous...
Read more
Why Personal Umbrella Insurance Is Worth a Second Look
March marks National Umbrella Month, and while it may sound like it’s all about rainy weather gear, it actually highlights something far more financially significant: personal umbrella insurance....
Read more
Essential Home Insurance Riders: Are You Covered?
Many homeowners mistakenly believe their insurance policy covers everything. However, they often discover gaps when they need it most. Optional add-ons, known as home insurance riders, can cover...
Read more
Celebrating Teen Driving Awareness Month: Key Insights and Safety Tips
Read more
Protecting Your Holiday Treasures: A Guide to Insuring Valuables
The holiday season is filled with joy, excitement, and the cherished tradition of gift-giving. As you unwrap those treasured presents, whether it's jewelry, electronics, or collectibles, it's...
Read more
Winter Home Prep: Stay Warm and Protect Your Space
As the chill of winter begins to set in, the thought of keeping your home cozy and secure becomes a top priority. It's understandable to feel concerned about maintaining warmth and safety, but with...
Read more
August's Traffic Awareness: A Back-to-School Reminder
Embracing the Back-to-School SeasonThe start of a new school year is a thrilling time filled with anticipation and a touch of chaos. Whether you’re packing small lunches or shopping for the perfect...
Read more
Comprehensive Boat Insurance in Fort Myers: What You Need to Know
Understanding Boat Insurance CoverageWhen it comes to protecting your prized vessel in Fort Myers, having the right boat insurance is crucial. Typically, a standard policy covers physical damage,...
Read more
Celebrating Mother's Day: Honoring the Dedication of Moms
Read more
Why Liability Insurance in Marco Island is Essential for Homeowners and Businesses
Living and working in Marco Island offers plenty of perks—beautiful beaches, thriving tourism, and a close-knit community. However, with these benefits come risks, making liability insurance in...
Read more
Local Boat Insurance in Estero: Protecting Your Watercraft Year-Round
Boating in Estero offers incredible opportunities to explore Florida’s beautiful waters, whether cruising along Estero Bay or fishing in the Gulf of Mexico. However, owning a boat also comes with...
Read more
Best Motorcycle Insurance in Naples: What Riders Should Look For
If you're a motorcycle enthusiast in Naples, you already know that Florida's roads offer some of the best riding experiences. But before you hit the open road, it's crucial to have the right...
Read more

Embrace Protection: National Umbrella Month & Insurance
As we celebrate National Umbrella Month in March, it’s a perfect time to consider the protection umbrellas provide. Just as a physical umbrella shields us from the unpredictability of the weather,...
Read more
What Insurance Do Small Businesses Need in Sanibel Island?
Owning a small business in Sanibel Island comes with unique challenges and risks, from unpredictable weather to liability concerns. Whether you run a boutique, restaurant, or service-based business...
Read more

Navigating Rising Insurance Premiums
Read moreView more